Source-linked register
Credit comparison: before 2014, 2014–19, 2019–24 and 2024–2026
The evidence supports different milestones under different governments. The fiscal-year tables below are accounting windows, not an audited party scorecard: governments change during a financial year, and a successor may pay for its predecessor's work.
On a small screen, scroll the table sideways to see every column and its sources.
| Period | Money record | Work and permission milestones | Credit boundary | Sources |
|---|---|---|---|---|
| Inception–2014 | ₹1.76 crore booked in 1995–96; ₹12.97 crore cumulative by March 2004; ₹3,454.43 crore carried at 1 June 2014 under the named capital head. | Investigation in 1991; first DPR in 1994; foundation on 5 March 1996, as recalled by Naidu; major package approvals from 2004; wildlife, environmental/R&R and forest decisions in stages. | These balances predate the three recent comparison periods. The initial DPR's separate cost is not isolated. May 2014 final forest permissions predate Naidu taking office on 8 June. |
|
| 2014–19 · TDP-led government | Original main-head BE across FY2014–15 to FY2018–19: ₹964.53 crore, plus separately identified supplementary demands and the SC provision. The main-head accounts series has a material 2017–18 booking discrepancy. | Construction continued; head-regulator and tunnel components were re-entrusted in 2017–18. The High Court required fresh consideration of the tunnel-deletion decisions. | Minister's ₹1,319 crore and Naidu's ₹1,414 crore spending claims differ. Neither is established as a like-for-like, all-heads tenure total by the archived accounts. |
|
| 2019–24 · YSRCP government | FY2019–20 to FY2023–24 main-head BE: ₹4,003.53 crore; gross budget Accounts: ₹516.68 crore. A separate 2026 report puts works at ₹981 crore, payments at ₹841 crore and pending bills at ₹140 crore. | Tunnel excavation milestones were reported in 2021 and January 2024; the March 2024 ceremony still left land/R&R and delivery work. The 2021 Union records did not accept deemed central approval. | ₹516.68 crore is a five-financial-year, single-head series—not all project spending or exact tenure cash. ₹981/₹841/₹140 are reported government figures, not an archived reconciliation. |
|
| 2024–2026 · TDP-led coalition · through 31 August | FY2024–25 gross main-head Accounts: ₹284.43 crore. FY2025–26 RE: ₹374 crore, not actuals. The government separately claims ₹2,400+ crore spent in two years and ₹768 crore R&R paid in three tranches. | The May 2026 interim order permitted TBM removal without deciding the monetary claims. A trial run was reported on 30 August and Phase I water release on 31 August. | Do not add R&R or the ₹140 crore inherited-bill payment to the ₹2,400+ crore claim without a ledger: components may already be included. Phase I release is not proof of full-command irrigation. |
- BE = original Budget Estimate; RE = Revised Estimate; Accounts = expenditure recorded for a completed financial year. A budget authorization, an administrative sanction, a release order and a settled payment are different stages.
- Naidu's 2014 government began on 8 June; Jagan's began on 30 May 2019. FY2019–20 and FY2024–25 straddle changes of government. FY2026–27 extends to March 2027, beyond this research cut-off.
- All calculated totals use the unrounded source values. The archive does not yet support a single fully reconciled cash-spending total for each political tenure.
Source-linked register
Before 2014: the DPR, foundation and early money trail
Historic Finance Accounts preserve the named Veligonda capital balance. Cumulative balances already contain earlier years: never add every row of this table together. The original rupee/thousand/lakh units were converted to crore; the scanned 1995–96 and 2003–04 tables were checked visually.
On a small screen, scroll the table sideways to see every column and its sources.
| Date / accounting window | Annual amount (₹ crore) | Cumulative amount (₹ crore) | What is actually documented | Sources |
|---|---|---|---|---|
| 1991 investigation / 1994 first DPR | Not separately isolated | Not separately isolated | CAG dates these stages, but does not give the first DPR's preparation bill. Investigation spending under general heads is not proved to be zero. | |
| FY1995–96 · foundation-year accounts | 1.7619003 | 1.7619003 | ₹1,76,19,003 under 4701-01-138 Valigonda. This is booked capital expenditure, not a certificate that this entire amount purchased construction or foundation-event arrangements. | |
| FY2003–04 | 0.0966 | 12.9738 | Annual ₹9.66 lakh; cumulative ₹12.9738 crore by 31 March 2004. The cumulative figure contradicts a blanket claim that only ₹10 lakh had been spent before 2004. | |
| FY2011–12 | 608.3688 in later budget Accounts | Not used for a cumulative bridge | The 2013–14 demand book supplies this annual figure. Different published accounting/reporting series must not be silently spliced. | |
| FY2012–13 | 342.0082 | Not independently reconstructed here | Original BE ₹599.90 crore; RE ₹504.3338 crore. Later Accounts record ₹342.0082 crore, not the allocation. | |
| FY2013–14 / 31 March 2014 | 226.9242 in Finance Accounts | 3,427.3177 | Original BE ₹402 crore. Later demand-book Accounts show ₹226.9243 crore: a ₹1,000 presentation difference from the Finance Accounts, not a new payment. | |
| 1 June 2014 bifurcation boundary | Not an annual payment | 3,454.4251 | The 2014–15 accounts carry this pre-bifurcation balance separately. It is not spending by the government that took office on 8 June. |
- A continuous annual ledger for 1991–2010, general investigation charges and a DPR-specific voucher have not been recovered. The cumulative accounts preserve historic booked amounts but do not identify every work or recipient.
- The named capital head is 4701-01-138 in the early accounts and 4700-01-138 in the later budget series. These figures exclude separately classified revenue interest and any spending not reconciled into this head.
Source-linked register
2014–19: allocations, revisions and recorded expenditure
Main project head 4700-01-138 only. These are fiscal-year rows, with actuals taken from later demand books or Finance Accounts. Supplementary demands and the separately classified SC provision appear in the next register.
On a small screen, scroll the table sideways to see every column and its sources.
| Financial year | Original BE (₹ crore) | RE (₹ crore) | Booked Accounts (₹ crore) | How to read it | Sources |
|---|---|---|---|---|---|
| 2014–15 | 76.58 | 76.58 | 202.0144 · 2 June–31 March | Finance Accounts cover the post-bifurcation interval, not a full twelve months or Naidu's exact tenure. An additional ₹155 crore supplementary demand was made. | |
| 2015–16 | 153.8920 | 268.9417 | 315.4935 | Actual expenditure exceeded both the original BE and the displayed RE. Neither is the complete final appropriation ledger. | |
| 2016–17 | 200.00 | 199.4150 | 250.5547 | This main-head row does not include the separate ₹20 crore SC-component budget provision. | |
| 2017–18 | 200.00 | 302.1185 | NIL in Finance Accounts; departmental figure 275.43 | The later budget Accounts column has no booked figure. CAG explicitly records the discrepancy. It is not evidence that no work or expenditure occurred. | |
| 2018–19 | 334.0548 | 341.3147 | 341.3147 | CAG's departmental series is ₹343.40 crore. Retain the distinction. Supplementary demands raise the located authorization above original BE. | |
| Scoped summary · not a party total | 964.5268 · original BE sum | Not a total of final grants | 1,109.3773 · sum of the four numeric Accounts rows | The numeric sum leaves out the disputed 2017–18 departmental amount and separately classified spending. Do not label it total TDP spending. |
|
- The ₹1,109.3773 crore subtotal is 202.0144 + 315.4935 + 250.5547 + 341.3147. Adding ₹275.43 crore from a different departmental series would create an unreconciled hybrid.
Source-linked register
Money outside the headline allocation: supplements and other heads
Original BE understates the authorizations visible in the supplementary books. Conversely, a supplementary demand or a provision under a separate head does not prove that money was released or spent.
On a small screen, scroll the table sideways to see every column and its sources.
| Record | Amount (₹ crore) | Scope and accounting treatment | Sources |
|---|---|---|---|
| FY2014–15 supplementary demand | 155.00 additional | Dam works/land ₹14.32 crore and canal works ₹140.68 crore. Spending authority requested through the supplementary book; not a cash-release certificate. | |
| FY2016–17 SC component | 20.00 BE and RE | 4700-01-789-11-18: works ₹15 crore and land ₹5 crore, separately from the ₹200 crore main-head BE. Actual disbursement is not established by this provision. | |
| FY2017–18 supplementary demand | 137.4999 additional | Located original BE plus supplementary demand is about ₹337.50 crore, consistent with CAG's rounded ₹338 crore allocation. It is not a ₹338 crore spending figure. | |
| FY2018–19 supplementary demands | 19.6595 + 48.6956 = 68.3551 | September and February project-only demands. Adding original BE ₹334.0548 gives ₹402.4099 crore, consistent with CAG's rounded ₹402 crore allocation. | |
| Revenue interest · FY2012–13 and FY2013–14 | 311.42 in each year | 2700-01-137, SH80, object 450: separately recorded interest. The 2014–15 BE/RE also carry ₹311.42 crore, but that is not verified 2014–15 actual expenditure. Do not describe this as cash paid for tunnel construction. |
- These are identified supplements and separate heads, not an exhaustive appropriation/reappropriation reconciliation. No all-years capital-plus-revenue total is asserted.
Source-linked register
2019–24: allocations versus the main-head Accounts series
Amounts are ₹ crore under the Ongole project head, gross as shown in the demand books. The five-year window includes April–May 2019 before the YSRCP government took office; it cannot by itself certify exact tenure spending.
On a small screen, scroll the table sideways to see every column and its sources.
| Financial year | Original BE (₹ crore) | RE (₹ crore) | Booked Accounts (₹ crore) | How to read it | Sources |
|---|---|---|---|---|---|
| 2019–20 | 485.10 | 100.7395 | 100.7396 | CAG separately records departmental expenditure of ₹333.86 crore. Government turnover occurred inside this financial year. | |
| 2020–21 | 965.4123 | 113.3512 | 114.2145 | CAG's departmental series instead records ₹318.21 crore. This mismatch requires a head-wise reconciliation before any cross-government spending comparison. | |
| 2021–22 | 1,595.3868 | 294.8540 | 174.5008 | RE was still an estimate: the later Accounts figure is materially lower. | |
| 2022–23 | 856.1508 | 256.5120 | 100.3749 | The separate ₹11.59 crore SASCI loan release for Tunnel I is a financing source, not additional expenditure to add to this row. | |
| 2023–24 | 101.4752 | 26.8478 | 26.8478 gross | The 2024–25 Finance Accounts show ₹26.8303 crore net for this previous year. Gross/net and recovery entries must be kept separate. | |
| Five financial years · main head only | 4,003.5251 | Not summed as spending | 516.6776 gross | Calculated from the five rows, not the whole project's cash spending. The four full years FY2020–21 to FY2023–24 alone record ₹415.9380 crore gross. |
- The Minister's October 2024 figure of ₹3,518 crore allocation closely matches the four original BEs for FY2020–21 through FY2023–24 (₹3,518.4251 crore), not all five FY2019–24 BEs.
- A blanket ₹170 crore spending total is not reconciled to even the four complete financial years above. That accounting inconsistency does not establish deliberate deception or resolve the wider departmental spending series.
Source-linked register
2024–2026: actuals available, estimates still pending
The research cut-off is 31 August 2026. FY2024–25 is the latest completed-year project Accounts column located in the archived budget series. Later estimates must not be relabelled as releases or expenditure.
On a small screen, scroll the table sideways to see every column and its sources.
| Financial year | Original BE (₹ crore) | RE (₹ crore) | Booked Accounts (₹ crore) | How to read it | Sources |
|---|---|---|---|---|---|
| 2024–25 | 393.4958 | 300.5231 | 284.4324 gross / 284.4323 net | This transition financial year includes the outgoing government before the coalition took office. The gross/net figures come from different official presentations. | |
| 2025–26 | 309.1345 | 374.00 | Not located | ₹374 crore is the RE printed in the 2026–27 budget, not a certified final actual or a payment ledger. | |
| 2026–27 · partial year at cut-off | 492.90 | Not yet in this archive | Not located | The budget year ends in March 2027. Do not count the whole ₹492.90 crore as money spent by August 2026. | |
| 2026–27 BE components | 300.00 dam + 82.90 canals + 110.00 R&R | Not expenditure | Not expenditure | Canals include ₹78 crore works and ₹4.90 crore land; R&R includes ₹80 crore compensation and ₹30 crore works. These components already sum to ₹492.90 crore. |
- FY2024–25 gross recorded spending comprises dam/appurtenant works ₹239.0390 crore, canals ₹28.5121 crore and R&R works ₹16.8813 crore. This is not proof that the later ₹768 crore R&R announcement was paid through these same entries.
Source-linked register
Actual releases and payments: what can be proved, and what is only reported
The strongest located project-specific release record is Parliament's SASCI loan table. Later R&R and two-year spending figures are attributed government statements in news reports; individual bank credits, CFMS bills and the complete release-order chain are not archived.
On a small screen, scroll the table sideways to see every column and its sources.
| Record / date | Amount (₹ crore) | Evidence category | Limit / double-counting risk | Sources |
|---|---|---|---|---|
| FY2022–23 SASCI · Lok Sabha reply 8 December 2025 | 11.59 | Primary record: central special-assistance loan released for Veligonda Tunnel I | The table reports that component as Work Completed. It does not certify the whole project, pay a named contractor, or supply water-project appraisal approval. Financing receipts overlap spending. | |
| April 2025 · critical impounding works | 106.39 | Reported administrative approval: G.O.Rt.No.184 | The report identifies MEIL ₹53.44 crore and SCL Infratech ₹29.38 crore assignments, with Finance endorsement on 25 April. The full signed G.O., BRO and settled bills remain unarchived. | |
| Inherited contractor bills · reported in March/August 2026 | 140.00 | Government claim: coalition cleared bills for earlier works | Credit for executing a work and credit for paying its bill belong on different dates. This is not a new ₹140 crore construction addition to the already reported ₹981 crore works value. | |
| June 2026 R&R ceremony | 300.00 cheque / 2,351 people reported | Reported distribution event | Do not add this to the later first-tranche ₹318 crore or the ₹768 crore total: the overlap and beneficiary definitions are not reconciled. | |
| R&R first tranche · recapped 22 August | 318.00 · 2,557 families | Government payment claim carried by PTI | Included in the three-tranche ₹768 crore total; individual settled payments are not independently verified. | |
| R&R second tranche · recapped 22 August | 200.00 · 1,622 families | Government payment claim carried by PTI | Included in the three-tranche total, not additional to it. | |
| R&R third tranche · 22 August | 250.00 · 2,027 families | Reported cheque distribution / government payment claim | 318 + 200 + 250 = ₹768 crore; 2,557 + 1,622 + 2,027 = 6,206 families. A ceremony is not beneficiary-bank reconciliation. | |
| 28–30 August R&R figures disagree | 905.00 versus 768.00 | Minister reported ₹905 crore paid to 7,027 households; 30 August release repeated ₹768 crore to 6,206 families | These claims have different stated coverage. Without village-wise sanctions, dates and payment IDs, they cannot be reconciled or treated as separate additive payments. | |
| Additional ex gratia · announced August 2026 | 169.00 | Announcement / reported sanction | Reported provision for further eligible displaced persons, including those turning 18 after 2019. Not evidence that ₹169 crore was already paid; do not add it as settled expenditure. | |
| Coalition's two-year spending claim · 30 August | More than 2,400 | PTI attributes this to a government release | No itemised all-head ledger is attached. Do not add R&R, cleared arrears, work approvals or annual Accounts to this headline figure. | |
| Budget release procedure · G.O.Ms.No.19, 9 April 2026 | Not a Veligonda payment amount | Primary statewide release-control instructions | CBRO/CFMS authorisation permits expenditure within controls; a project allocation or a general release order does not by itself prove a contractor or displaced family received money. |
- The release/payment column deliberately contains evidence-status labels. A missing public payment ledger is an evidence gap—not proof that payment did not happen.
Source-linked register
Why the spending numbers disagree
CAG itself prints two different series. Departmental project expenditure, Treasury/Finance Accounts, work-agreement values and cumulative balances measure different things. No unexplained difference is labelled missing or misappropriated money.
On a small screen, scroll the table sideways to see every column and its sources.
| Record | Figure (₹ crore) | What can and cannot be added | Sources |
|---|---|---|---|
| FY2017–18 · CAG comparison | Department 275.43 / Finance Accounts NIL | A visible reporting discrepancy. Do not convert a NIL book entry into a claim that the project had zero expenditure. | |
| FY2018–19 · CAG comparison | Department 343.40 / Finance Accounts 341.31 | Different series; later demand-book Accounts retain 341.3147. | |
| FY2019–20 · CAG comparison | Department 333.86 / Finance Accounts 100.74 | The departmental figure includes price variation, reimbursements, land and R&R; the exact bridge to booked heads is missing. | |
| FY2020–21 · CAG comparison | Department 318.21 / Finance Accounts 114.21 | CAG's four-year departmental sum is ₹1,270.90 crore. It is not the sum of the Finance Accounts column. | |
| Departmental cumulative snapshot · 31 August 2015 | 3,829.03 | WRD profile: works 3,091.87 + land 267.45 + R&R 22.65 + forest 437.04 + others 10.02. Its Apr–Aug 2015 amount, ₹98.49 crore, is already included. The archived web snapshot was captured in 2022 but the financial data are from 2015. | |
| CAG's departmental cumulative series | 4,377.36 through FY2016–17; 5,648.26 through FY2020–21 | The second figure is the first plus ₹1,270.90 crore. Both are cumulative; do not add them together or to subsequent whole-project totals. | |
| March 2025 capital-account stock | 1,910.4690 + 3,454.4251 = 5,364.8941 | The first amount is post-bifurcation expenditure-to-date; bold ₹3,454.4251 crore is legacy un-apportioned expenditure. Their arithmetic sum is a named-head capital stock, not current-government spending or an all-heads project total. | |
| June 2026 government-reported project totals | Cost 10,580; spent 6,736; balance 3,844 | These are reported departmental totals, not the same March 2025 named-head stock. They should not be used to manufacture a precise tenure split. | |
| 2019–24 works versus cash · August 2026 report | Works 981; reportedly paid 841; pending 140 | This reported decomposition is internally additive (841 + 140 = 981), but the underlying bills are not archived. Later payment of 140 changes payment timing, not the original works value. |
- The full reconciliation requires treasury head/object codes, gross expenditure and recoveries, booked interest, deposit/P.D. accounts if used, work-measurement certificates, pending liabilities and payment dates. None is supplied merely by announcing a project-wide total.
Source-linked register
Administrative sanctions: what the State authorised, not what it paid
The archived official WRD profile lists these orders and amounts as of August 2015. Its list explicitly includes revised orders, so the entries are not a clean additive spending series. The standalone signed orders are still needed to resolve supersession and conditions.
On a small screen, scroll the table sideways to see every column and its sources.
| Order / date | Amount (₹ crore) | Purpose and limit | Sources |
|---|---|---|---|
| G.O.120 · 9 July 2004 | 765.00 | Stage I: irrigation, drinking water, Tunnel I and associated works. Administrative approval, not expenditure. | |
| G.O.164 · 8 October 2004 | 469.49 | Revised Sunkesula and Gottipadia gap-closing estimates. | |
| G.O.104 · May 2006 | 776.00 | Second tunnel. The profile's sanctions table says 31 May but its narrative gives 1 May; the signed order is needed to settle the day. | |
| G.O.378 · 15 June 2006 | 0.10 | Preliminary investigation of Western Canal km 0–110. This is not the cost of the first 1994 project DPR. | |
| G.O.98 · 16 April 2007 | 3.384 | Transfer of part of the feeder canal from Package II to Package I. | |
| G.O.105 · 19 April 2007 | 156.15 | Ultimate-stage feeder widening and raising Sunkesula, Gottipadia and Kakarla dams. | |
| G.O.10 · 22 January 2008 | 13.765 | Additional Teegaleru Canal work in Package II. | |
| G.O.83 · 8 May 2008 | 488.16 | Land acquisition and rehabilitation/resettlement. | |
| G.O.87 · 12 May 2008 | 20.00 | R&R benefits for Chintalamudipi, Gundamcherla and Katamraju Thanda. | |
| Memo 7599 · 21 January 2009 | 212.61 | Additional Eastern Main and link canal works for ultimate discharge, km 0–44.625. | |
| G.O.31 · 19 February 2009 | 739.26 | Western Branch Canal, Seetham Sagar reservoir and Racheruvu improvements. | |
| G.O.32 · 19 February 2009 | 1,129.50 | Eastern Main Canal beyond km 44.625, including Udayagiri Branch Canal. | |
| Memo 24671 · 6 March 2010 | 4.89 | Additional ultimate-section feeder-canal work in Package II. | |
| No order/date specified in profile | 363.3845 forest / 8.3100 quality control | Afforestation/forest net present value and third-party quality control for Packages VI–VII. Not a separately verified cash-release record. | |
| Later works agreements / April 2025 approval | 277.00 / 106.39 | CAG records an April 2022 Tunnel II supplemental agreement of ₹277 crore. April 2025 reporting records ₹106.39 crore of critical works approval. Different instruments and scopes—not amounts to add blindly to old sanctions. |
- The profile states an overall ₹5,150 crore sanction figure. Because it includes revised orders and separately described ancillary amounts, this dossier does not manufacture a new total by summing every row.
Source-linked register
Permissions received—and the approvals not established
Environmental clearance, wildlife recommendation, forest diversion, R&R approval, budget sanction and central water-project appraisal are separate decisions. Receipt of one does not prove receipt or continuing compliance with all the others.
On a small screen, scroll the table sideways to see every column and its sources.
| Permission / date | What the record establishes | Limit / later issue | Sources |
|---|---|---|---|
| Feasibility / DPR / environmental / R&R · by July 2012 | CAG's clearance matrix, row 21, marks all four as received for Veligonda. | The same row marks CWC in-principle, forest and investment clearances as not received at that cut-off. The standalone environmental and R&R approval letters, dates and conditions are not archived. | |
| NBWL Standing Committee · 19 February 2008 | Conditional wildlife recommendation for the tiger-reserve diversion, with fifteen conditions. | Not a substitute for forest clearance, environmental-clearance conditions or central water appraisal. | |
| Forest Stage I · 30 September 2009 | In-principle forest approval recorded by CAG. | A first-stage permission, not final diversion authority; the July 2012 matrix still marks forest clearance not received. | |
| Forest final approval · 9 May 2014; State G.O.59 · 31 May | Union final approval 8-71/2007-FC and State permission, subject to conditions, are recorded in CAG. | Both precede the TDP government's 8 June 2014 swearing-in. Later compliance is a separate question; signed standalone letters are not yet archived. | |
| Forest compliance · 2010–13 and June 2019 | FAC documents pre-final work affecting 37.756 hectares; CAG records a later debris-dumping offence report over three hectares. | Administrative violation/offence records are not final criminal convictions. Final disposal of the proceedings is not archived. | |
| Water appraisal · 2012 audit | CAG says CWC had not approved Veligonda because firm water availability was not established. | This historical record should not be rewritten as a claim that no proposal had ever been considered at any time. | |
| KRMB Gazette · 15 July 2021 | The notification lists Veligonda head works and Nallamalasagar as ongoing, unapproved and non-operational. | This is the dated regulatory classification, not a claim that August 2026 water release did not occur. No later approval changing the classification is archived. | |
| AP's deemed-approval argument / Union reply · 13 December 2021 | AP cited the Reorganisation Act's Eleventh Schedule and the Venegondu/Veligonda naming issue. The Union said inclusion did not confer deemed approval; DPR/proposal had not been received for the stated KRMB/CWC appraisal process. | The reply said KRMB/Apex and the Advisory Committee approvals had not been obtained. It answers AP's argument; the complete later correspondence remains missing. | |
| Changed excavation method · 2020–22 | CAG records the State's expert-assessment requirement and April 2022 manual-excavation agreement. | The State said no additional mandatory permission was needed; CAG rejected the response because evidence of its own required assessment was not supplied. This does not erase the earlier project EC. | |
| Continuing interstate objection · February 2026 | Telangana's engineer-in-chief reportedly sought KRMB action over AP projects and alleged expansion of Veligonda and other schemes. | An attributed interstate objection, not a new court judgment or final KRMB finding. The underlying letter and final determination are not archived. |
- A 2022–23 financing release, a 2024 tunnel inauguration and a 2026 Phase I release do not themselves supply missing appraisal orders or demonstrate compliance with every approval condition.
Claim versus record
What the record shows
Each lane keeps the public claim, the editorial finding, and the controlling records visually separate.
Only ₹10 lakh was spent on Veligonda before 2004, all on the foundation event
Jagan made that claim on 31 August 2026. The official 1995–96 Finance Accounts record ₹1.7619003 crore under Valigonda, and the 2003–04 accounts record ₹12.9738 crore cumulatively by March 2004. These are booked capital figures—not evidence that all the money bought physical construction, or an itemised account of the foundation ceremony. The original DPR's separate bill is still missing.
The published ₹1,319 crore versus ₹170 crore comparison settles TDP and YSRCP spending
The Minister quoted those amounts in October 2024; Naidu later quoted ₹1,414 crore for 2014–19. The main-head demand books alone record ₹415.9380 crore gross in the four complete financial years FY2020–21 to FY2023–24, so ₹170 crore is not supported as an all-project total. CAG also prints materially different departmental and Finance Accounts series. The 2026 report of ₹981 crore works, ₹841 crore paid and ₹140 crore arrears is another attributed account, not an audited bridge between them.
A budget allocation or revised estimate is money released and spent
For FY2021–22, the main-head BE was ₹1,595.3868 crore, RE ₹294.8540 crore and later Accounts ₹174.5008 crore. The current ₹374 crore FY2025–26 RE and ₹492.90 crore FY2026–27 BE are not verified actuals. Parliament does separately document a ₹11.59 crore SASCI loan release for Tunnel I in 2022–23; that is financing, not an extra work-payment amount to add to expenditure.
One government can claim all the tunnel construction and the final water release as its own work
The foundation, package awards, re-entrustments, excavation breakthroughs, TBM removal and first-phase release occurred at different times. Jagan's claimed excavation split—20.333 km in 2004–14, 6.686 km in 2014–19 and 10.568 km in 2019–24—is included as his claim, not as independently certified measurement-book quantities. The 2004–14 period must not be attributed in its entirety to Y. S. Rajasekhara Reddy personally. The 31 August 2026 release is a later operational milestone; it does not erase earlier excavation or establish full-command delivery.
The Veligonda project was completed when the twin tunnels were inaugurated in March 2024
The March 2024 tunnel inauguration was a real milestone, but the same report said another ₹1,200 crore was needed for land and R&R before reservoir filling. Trial-run postponement and continuing Tunnel II work were reported on 22 August 2026. Subsequent reports record a successful trial on 30 August and Phase I water release on 31 August. The 10.70-TMC Phase I plan and 1.19-lakh-acre target are not measured proof that that entire volume or command has already been served.
Veligonda had every necessary central permission because forest and wildlife approvals were issued
CAG's July 2012 matrix records environmental and R&R clearances as received. The archive also supports a conditional wildlife recommendation in 2008 and final forest-diversion approval in May 2014, before the June 2014 TDP government took office. These do not substitute for water-project appraisal: the July 2021 KRMB notification classified Veligonda's head works as unapproved, and the December 2021 Union reply rejected AP's deemed-approval argument. No later order changing that classification is archived here.
Completing the two tunnels guarantees drawal of 43.50 TMC and irrigation of the full command
The 43.50-TMC figure is a design target. CAG found no project-specific scientific water-availability study in the supplied record, identified a bed-level difference that could leave about 4.11 km of standing water in Tunnel II, and found the feeder canal designed for 328 cumecs against a 483.32-cumec tunnel maximum. Distribution networks were also incomplete at the audit cut-off.
Contractor delay alone explains the cost and schedule overrun
Contractor performance and repeated re-entrustment were material. The department also attributed delay to land handover, unpaid compensation, forest land, scope and design changes, additional quantities and sand availability; CAG added delayed preliminary clearances and planning defects. The archive does not support assigning the entire overrun to a single contractor or government term.
The stuck Tunnel II TBM was only an engineering problem
The obstruction became a linked payment-and-ownership dispute. ICICI Bank's W.P.No.14245/2020 claimed about ₹62.85 crore plus interest in TBM lease rentals and initially secured a restraint on third-party rental disbursements. HCC-CPPL's W.P.No.33775/2023 pleaded a separate ₹479.82 crore claim covering TBM and equipment use, costs and losses, and its anti-dismantling interim protection was extended in June 2024. On 4 May 2026, the High Court allowed the State to disassemble the machine in the public interest while directing a committee to determine the HCC-CPPL amount within four months. It did not decide either money claim on the merits.
CAG's excess-payment findings prove corruption or criminal liability
CAG quantified avoidable burdens, excess payments, boosted benchmarks and idle equipment. Those are audit findings requiring recovery, departmental or legal follow-up; they are not themselves convictions or findings of corrupt intent. The archived contractor judgments concern natural justice, price-escalation reconsideration and compensation procedure, not criminal guilt.
Chronology
Timeline
Follow the record in sequence; every event opens to its supporting source.
State orders feasibility investigation
Andhra Pradesh ordered an assessment of feasibility and investigation for a drought-mitigation project that would later become Poola Subbaiah Veligonda.
First detailed project report prepared
The first DPR was prepared. CAG later found the project proceeded through multiple piecemeal administrative approvals and technical sanctions.
Foundation milestone and an early booked expenditure
Naidu's later account dates the foundation to 5 March 1996. The official 1995–96 Finance Accounts record ₹1.7619003 crore under Valigonda; they do not split that expenditure into DPR preparation, administration, civil works or ceremony costs.
Budget says grounding steps have begun
The State's budget speech said steps had been initiated to ground Veligonda as part of a Krishna-basin construction push.
Capital accounts preserve the pre-2004 spending baseline
The named project head records ₹12.9738 crore cumulatively, including ₹9.66 lakh in FY2003–04. This is a historic capital-account balance, not a certificate of how much tunnel excavation had been achieved.
Administrative sanction and first package awards
G.O.Ms.No.120 authorised commencement in July. By November, Package II for Sunkesula, the feeder and Teegaleru and Package III for Gottipadia had been awarded under EPC contracts.
Flood-day assumption changes; Tunnel I starts
The State reduced the design draw window from 45 to 30 flood days in April. Execution began in August, including the Tunnel I EPC agreement with Sabir Sew Prasad JV.
Tunnel II contracted; forest proposal submitted
HCC-CPPL signed the ₹735.21 crore Tunnel II agreement on 21 June. The State submitted a 3,069.91-hectare forest-diversion proposal in July.
Wildlife recommendation and revised sanction
The NBWL Standing Committee recommended the tiger-reserve diversion with fifteen conditions. The 2012 audit records a ₹4,785.82 crore administrative sanction the following month.
Stage I forest approval issued
The Union Ministry issued Stage I forest approval. Final approval would not follow until May 2014.
Geological incident stops boring for 16 months
Loose soil and a gush of water halted tunnel boring. The department confirmed a sixteen-month stoppage to the 2012 audit.
Forest violations documented before final approval
Forest officers issued notices and offence records over tunnel, Eastern Main Canal and feeder work. The 2013 FAC agenda recorded 37.756 hectares affected by tunnel work without formal approval.
Environmental and R&R clearances recorded as received
CAG's clearance matrix marks feasibility, DPR, environmental and R&R clearance as received for Veligonda. The same matrix marks CWC in-principle, forest and investment clearances as not received at that cut-off. The original EC and R&R letters are still needed for exact grant dates and conditions.
First CAG review flags water and delivery risk
The Jalayagnam audit said no scientific study had established the flood days and water availability, and it recorded slow tunnel and feeder progress plus forest-land delay on the Eastern Main Canal.
Final forest approval and State permission
The Union Ministry issued final forest approval on 9 May and the State issued Stage II permission through G.O.Ms.No.59 on 31 May, both subject to conditions. These dates precede Naidu's 8 June 2014 swearing-in; the grant should not be assigned to his later 2014–19 term merely because it occurred in 2014.
Tunnel deletions trigger High Court intervention
The department deleted balance portions from the two tunnel contracts and moved toward fresh tenders. The High Court set the deletion orders aside for failure to consider the contractors' replies, while permitting fresh decisions after a hearing.
Balance tunnel work changes hands
Tunnel I moved from Sabir Sew Prasad to MEIL and then RR Edifice for the final manual reach. Tunnel II moved from HCC-CPPL to Rithwik and then to MEIL through reverse tendering.
Fourth reservoir gap identified late
The department identified a fourth gap below full-reservoir level and proposed a saddle dam. CAG said maximum storage was impossible without closing it.
Bank opens separate TBM lease-rental litigation
In W.P.No.14245/2020, ICICI Bank claimed about ₹62.85 crore plus interest in lease rentals for the Tunnel II boring machine. The first interim order restrained the State from disbursing TBM lease-rental amounts to third parties; it did not award the bank's claim or itself prohibit dismantling.
Tunnel I excavation and head works reach milestone
MEIL's account says it completed its Tunnel I excavation in January. The department told CAG that Tunnel I and its head regulator were complete in March, while connected feeder and distribution works remained unfinished.
Union notification lists Veligonda unapproved
The KRMB jurisdiction notification listed the head regulator, tunnels, appurtenant works and Nallamalasagar as ongoing, unapproved and non-operational.
Union answers AP's central-approval argument
A Rajya Sabha reply records AP's claim that the Reorganisation Act permits completion and operation, but rejects deemed approval. It says the DPR/proposal had not been received for the stated KRMB and CWC appraisal process and the relevant central approvals had not been obtained.
Long-running ex-gratia dispute closes without a payment finding
A 2009 order had directed consideration of one Veligonda landholder's compensation and ex-gratia claim. The High Court later found no contempt because a status-quo order in another writ had blocked payment, and closed the case without establishing whether the approved ex-gratia was ultimately paid.
Large package gaps remain; manual Tunnel II work added
At March cut-off, CAG recorded incomplete structures, canals and distributaries and only 17,906 of 28,529 acres acquired. In April, MEIL received a ₹277 crore supplemental agreement for manual Tunnel II excavation through adits.
High Court directs a compensation representation to be decided
In one land claimant's petition, the High Court directed the Special Collector to consider a compensation and R&R representation within two weeks. It did not adjudicate the claimant's entitlement on the merits.
Parliament identifies an actual financing release
The Lok Sabha annexure lists a ₹11.59 crore special-assistance loan released under SASCI for Veligonda Tunnel I. It reports that component completed; it is not a certification of project-wide completion or a new amount to add to expenditure.
Package II recovery memo set aside for reconsideration
The High Court set aside a proposed price-escalation recovery against Jaiprakash Gayatri and directed the State to reconsider entitlement under the applicable G.O.
Former Tunnel II contractor obtains anti-dismantling protection
HCC-CPPL's W.P.No.33775/2023 pleaded a ₹479.82 crore claim for TBM and other equipment use, costs and losses. In its interim application the JV asked that the machine not be dismantled; on 24 June 2024 the High Court extended the earlier interim order. The amount was a contractor claim, not a court award.
Tunnel II excavation breaks through
MEIL and project officials reported completion of digging through the second tunnel. Their forward-looking claim that water would be released in the next season was not itself proof of delivery.
Twin tunnels inaugurated; R&R still outstanding
The Chief Minister inaugurated the twin tunnels. The event report also said ₹1,200 crore remained necessary for land acquisition and R&R before reservoir filling.
Critical impounding works receive reported administrative approval
Reporting on G.O.Rt.No.184 identifies ₹106.39 crore of critical works approval, including assignments to MEIL and SCL Infratech. The signed G.O., release order and final payment records are still required to establish disbursement.
High Court separates TBM removal from the money claims
Hearing the HCC-CPPL and ICICI Bank writs together, the High Court declined to decide their merits at the interim stage. With the parties' consent and citing public interest, it directed a committee to determine the contractor amount within four months and allowed the State to disassemble the Tunnel II TBM in the meantime.
TBM dismantling starts inside Tunnel II
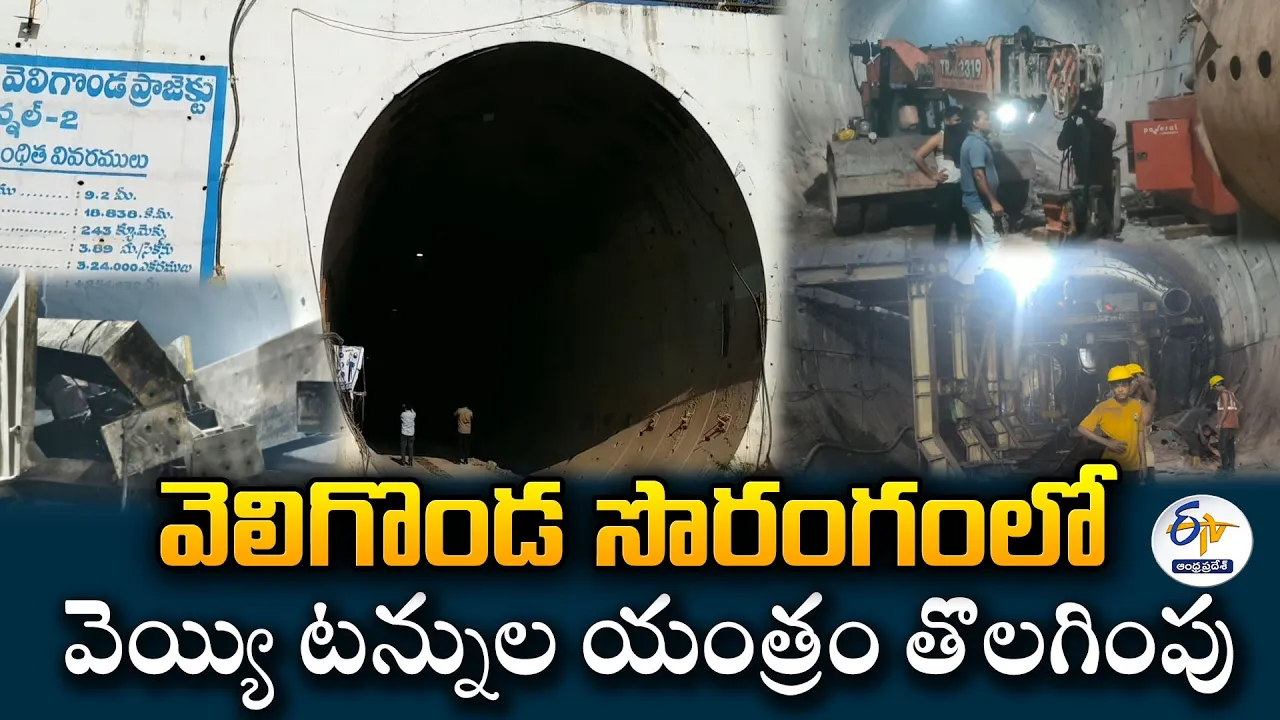
ETV documented the removal operation beginning inside the tunnel. By 17 June, the Water Resources Minister said three of seven machine compartments had been brought out and engineers were considering burying the complex cutter head in place.
Feeder-canal work and R&R remain active
During an inspection, the government distributed a ₹300 crore R&R cheque. The report quoted a total project cost of ₹10,580 crore, ₹6,736 crore spent and ₹3,844 crore still required; these are reported government figures, not audited final accounts.
Budget retains balance works, land and rehabilitation targets
The Outcome Budget sets targets for feeder and impounding work, 1,233 acres of land, six kilometres of tunnel-related balance work, payments to 7,255 displaced families and seven R&R centres. Targets are not evidence of final payment or completion.
TBM removal progresses; trial is postponed; R&R tranches reported
The Minister said on 15 August that 1,500 of the stuck TBM's reported 1,900 tonnes had been dismantled. A 22 August report still described a postponed trial and continuing Tunnel II work. Separately, PTI reported a third R&R tranche of ₹250 crore and a government-claimed three-tranche total of ₹768 crore for 6,206 families.
Successful trial run reported
Reporting published early on 31 August says officials held a successful trial on Sunday, 30 August. The initial 10.70-TMC impounding figure remains a plan, not a metered cumulative release certificate.
Phase I water release reported; credit dispute intensifies
The Hindu reports that Naidu inaugurated Phase I and released Krishna water into Nallamala Sagar. The same day's credit dispute concerns earlier spending, excavation and the March 2024 ceremony. The release establishes a first-phase operational milestone, not delivery of 43.50 TMC or irrigation of the full 4.38/4.47-lakh-acre command.
Evidence boundary
Supported and not established
The line matters: archived records can support a finding without resolving every allegation, motive, or final outcome.
What the sources support
- The project originated in a February 1991 feasibility order, had its first DPR in 1994, and entered package construction in 2004-07.
- Its design seeks to divert 43.50 TMC of monsoon floodwater through two tunnels and a feeder canal into Nallamalasagar for irrigation and drinking-water supply.
- CAG records environmental and R&R clearances as received by July 2012; wildlife and forest decisions were issued in stages, with conditions and documented work before final forest approval.
- Official capital accounts preserve ₹1.7619003 crore in 1995–96, ₹12.9738 crore cumulatively by March 2004, and a ₹3,454.4251 crore pre-bifurcation balance at 1 June 2014.
- The financial-year registers distinguish original BE, RE and booked Accounts. CAG itself identifies a material difference between departmental spending and Finance Accounts.
- Parliament documents a ₹11.59 crore SASCI loan release for Tunnel I; R&R payments and the coalition's two-year total are separately labelled government-reported figures.
- All seven packages had defined contractor scopes, and several tunnel, head-regulator, canal and distributary components changed contractors or contract form.
- CAG identified unresolved hydrology, tunnel-bed, feeder-capacity, reservoir-gap, contract-payment, land and distribution-network risks.
- High Court orders affected tunnel deletions, Package II recovery, the stuck Tunnel II TBM, an ex-gratia dispute and an individual compensation representation, but none of the archived orders is a criminal-liability finding.
- The stuck Tunnel II TBM became the subject of linked HCC-CPPL and ICICI Bank payment litigation; the May 2026 interim order allowed dismantling without adjudicating either monetary claim.
- Tunnel excavation milestones were reported by January 2024; a trial was reported on 30 August 2026 and a Phase I water release on 31 August. Full-command irrigation and metered delivery remain separate questions.
What remains unresolved
- No post-July 2021 KRMB, CWC, TAC or Apex Council order changing Veligonda's unapproved classification has been archived.
- CAG records environmental and R&R clearance as received by July 2012, but the standalone letters, exact dates, approved scope, validity conditions and amendments are not archived.
- No complete DPR-fee, inception-to-date all-heads, BRO/CFMS, contractor-bank or beneficiary-payment ledger has been recovered. Missing entries are not assumed to be zero.
- FY2019–20 and FY2024–25 straddle governments; the 2014 accounts start at bifurcation. Exact tenure totals require transaction dates and a works-versus-payment bridge. FY2025–26 actuals and April–August 2026 actuals are not established by RE or BE.
- The ₹1,319/₹1,414 crore TDP claims, ₹170 crore YSRCP comparison, ₹981/₹841 crore works/payment report and ₹2,400+ crore coalition claim have not been reconciled to one all-head accounting series.
- The ₹768 crore/6,206-family and ₹905 crore/7,027-household R&R claims have different coverage; village-wise payment IDs and settlement dates are required before reconciling them or adding any figure.
- The reported 31 August 2026 Phase I release does not certify a cumulative 10.70 TMC delivered, full reservoir storage, farm-level supply to 1.19 lakh acres, or completion of the full project.
- Current certified completion is missing for feeder lining, CM/CD structures, the saddle gap, all distributaries, Western Branch Canal, pressure mains and balancing reservoirs.
- Final land awards, village-wise R&R ledgers, physical relocation, compensation settlement and the 2026-27 targets have not been independently reconciled.
- The official May 2026 cause list is archived, but signed court PDFs for the linked TBM orders, the committee's four-month determination, later docket outcomes, the underlying 2008 land writs, appeals, arbitration awards and final contractor account closures are not yet archived.
- The latest project-specific hydrology and operations study needed to test flood days, water head, competing demands and feeder capacity is not in the archive.
- CAG financial findings have not yet been traced through recovery, acceptance, contest, write-off or reversal in final accounts.
Corrections
Changes to this report
Clearance clarification: CAG's July 2012 matrix records environmental and R&R clearances as received. The earlier version left receipt of a separate environmental clearance unresolved. The standalone approval letters, precise dates, conditions and amendments remain unarchived; this does not establish central water-project appraisal approval.
Controlling record